GCM Enterprise LLC · Monthly Business Review

Bank-trained analysis, every month.

For owner-run companies doing $1M–$100M: the analysis a fractional or outsourced CFO would run, without hiring one.

Each month I rebuild your financial model, track the risks, show where cash is heading and price each recommendation in dollars. First deep analysis within 15 days of read-only access.

Book a 30-minute call See a specimen brief 30 minutes · what I'd look at first in your numbers, whether your books are ready, and how the fixed fee is set

Signed by Graham Miller, former bank SVP · Typically $1,000–$3,000 a month, fixed · Month to month

Bluestone Creamery & CoffeeSpecimen Monthly Business Review · June 2026 · Café example; same brief in any sector What the receipts showed
Reported revenue growth+4.6%
Added Tuesday trading+$54,600
Same days, both years−$28,900
Read the full specimen

Who It's For

Built for owner-run companies with something to lose.

$1M–$100MOwner-run companies, from businesses ready for professional-grade financials to those large enough to need real analysis.

Any sectorServices, trades, manufacturing, e-commerce, healthcare. The levers are universal; only the dials change.

Virginia & nationwideBased in Virginia Beach. Available to companies across Virginia, from Hampton Roads to Richmond and Northern Virginia, and nationwide. The work is remote by design.

What You Get

I find the risks and price the improvements. You decide.

Accounting keeps the record straight. Analysis finds what moved and what it's worth. Forecasting says where it lands. Those are normally three hires, three bills, and three people who don't talk to each other. I run them as one purpose-built system, against the same reconciled data, every month.

See risk early

Before it's expensive

Margin drift, cash conversion, concentration, unbilled work, covenant headroom. Named with an ID, tracked with a direction, and reported until they close.

Improve on purpose

Priced, not suggested

Every recommendation carries the dollars it's worth and the cost of waiting, so priority stops being a matter of opinion.

Where I sit

Alongside your team

Between the people who keep your records and the decisions that move the business. Your bookkeeper, controller and CPA stay; I work from what they produce.

Getting Started

Deep analysis within 15 days.

No long discovery phase and nothing to install. Read-only access to your accounting system is enough to start, and your first deep analysis arrives within 15 days of that access. If the books are behind, I tell you in the first week what's usable and what catching up would take.

Days 1–3

Statements and one conversation

Counting from the day read-only access to your accounting system is granted: two to three years of statements and one conversation about how the business runs. By the end of the first week you know what's usable.

Days 4–14

I rebuild the model

Your levers mapped, your engine modeled from first principles, and the leaks located.

Day 15

Your first deep analysis

What's working, what's leaking, where cash is heading over the next 90 days, the risks that need a name, and the first recommendations, priced in dollars.

Then monthly

The standing cadence

After each close: a brief on what moved and why, risks tracked until they close, each recommendation priced, and last month's checked against what happened. Then we meet, I tell you what I'd actually do, and you decide.

Book a 30-minute call Timeline is typical and varies with the state of the books.

The Operator

Built in a bank. Sharpened by ownership.

I do the analysis, sign every brief, and meet with you each month. GCM isn't a software product or a pool of junior analysts.

Former bank SVP, Data & Analytics
led the function that turned institutional data into decisions
ALCO & Credit Risk
balance-sheet, liquidity & risk discipline at the committee level
Owner-Operator
I run this same playbook inside my own companies

The system anchors what gets found. The judgment comes from someone who has carried the risk.

Graham Miller, GCM Enterprise LLC

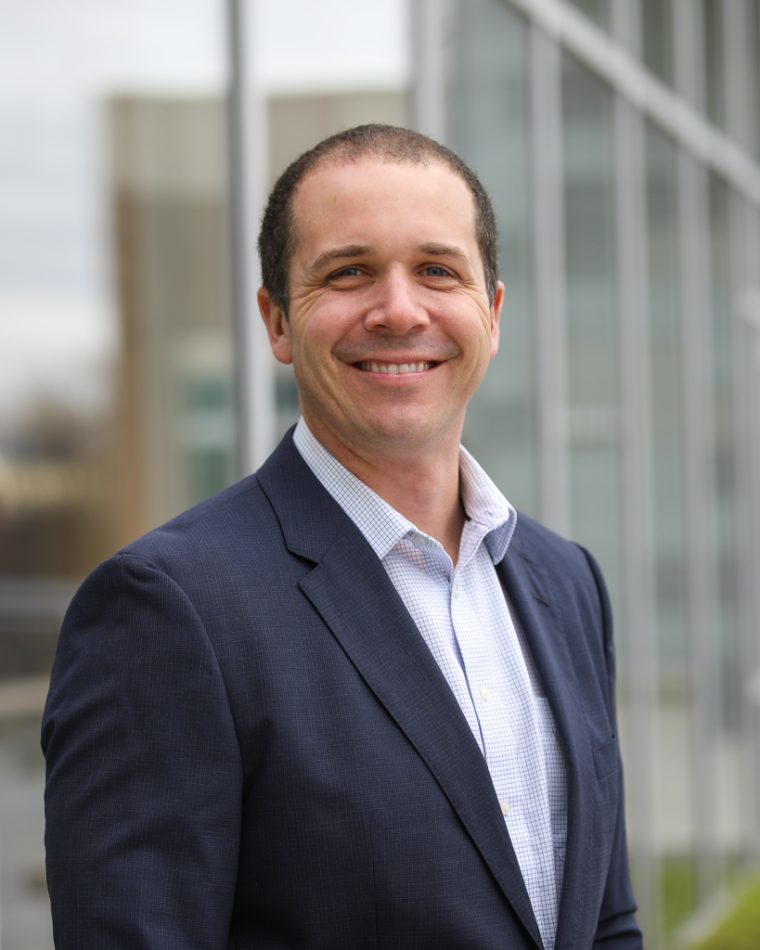
Graham MillerVirginia Beach, VA

The Deliverable

This is what lands on your desk.

The format of a client monthly review, filled in for a fictional café. Every figure, name and finding below is invented; the structure and depth are what a client receives. For a manufacturer the same brief runs on product lines, inventory and plant capacity; for a contractor or services firm, on jobs, crews and backlog.

Specimen — fictional company, illustrative figures. Client briefs are confidential.

GCM Enterprise

Monthly Business Review

Bluestone Creamery & Coffee

Period: June 2026  |  Incorporates receipt-level revenue analysis and margin evolution review  |  Prepared July 2026

Executive Verdict

June was the strongest month in the company's recorded history, and the improvement behind it is real — but it is a different improvement than the headline suggests. Revenue of $114,240 ran slightly below June last year; adjusted profit rose about three and a half times. The engine is cost, not demand: prime cost — ingredients plus labor together — has fallen almost sixteen points of revenue against the first half of last year, verified independently against actual vendor payments and payroll cash rather than the accounting entries. Cash finished at $88,470, the highest in eighteen months and nearly double the March forecast.

Receipt-level analysis completed this month adds essential context on revenue. The year-to-date increase of 4.6% is a calendar effect: the store added Tuesday trading this year, worth $54,600, while revenue on comparable days fell 5.1%. Underneath, the mix is shifting — coffee is up 31% and growing every single month, while scoop transactions are down 16% at unchanged prices and the evening trade is eroding. The business is becoming a morning coffee-and-bakery café that also sells ice cream. That is not a problem — coffee is higher-margin and far less seasonal — but it should become a deliberate strategy, and it directly shapes what the second location is designed to be.

Two things temper the month. Reported profit of $41,180 becomes roughly $31,500 after known bookkeeping corrections, and about $23,600 of merchandise stock sits on the balance sheet against sales that have largely stopped. Neither changes the direction; both need attention before the autumn.

Performance Dashboard

MetricCurrentPrior periodTrendStatus
Revenue (June)$114,240$118,905−3.9% YoYYELLOW
Comparable-day sales (H1)−5.1%—DecliningYELLOW
Gross margin (June, fees restored)74.5%63.9%+10.6 ptGREEN
Prime cost % (H1, adjusted)56.4%72.1%−15.7 ptGREEN
Net income (June, adjusted)$31,460$8,940~3.5×GREEN
Cash position$88,470$71,30018-mo highGREEN
Days of fixed costs covered148 days24 daysvs Nov-25 lowGREEN
Debt service coverage3.4×~1.2×CoveredGREEN
Bookkeeping corrections open$41K effect—July closeYELLOW

Revenue — What Is Actually Growing

Added Tuesday trading+$54,600
Decline on days open in both years−$28,900
Reported revenue growth+$25,700 · +4.6%

Opening Tuesdays was a sound decision — the revenue lands on a largely fixed cost base — but it is a lever that can only be pulled once. Any plan built on comparable-day performance starts from the honest number.

Coffee is the growth engine, up 31% and above prior year in every month of 2026 — and it holds through the winter far better than ice cream, which directly softens the November cash risk. Bakery, invisible in the accounting system until this analysis, is a quarter of the business and growing; the plan to move baking off site touches 24% of revenue, so the bought-in product has to be good. Ice cream is the decline: scoop transactions fell 16% at flat prices — fewer customers choosing ice cream, concentrated in evenings (−8.1%) and weekends (Saturday −6.5%, Sunday −9.6%).

Why scoop traffic is down is the most important open question in the business — competition, menu fatigue, pricing perception, or the same customers shifting spend to coffee and pastry. The data locates the decline precisely; it cannot explain it. It deserves an answer before the second location, which carries the ice cream brand, is committed.

Read the rest of the brief: margin, corrections, forward look

Margin — The Story Of The Year

Prime cost as % of revenue — trailing twelve months

JULAUGSEPOCTNOVDECJANFEBMARAPRMAYJUN

Prime cost — ingredients plus labor — is the standard measure of a food operation's engine room. Above 60% of revenue a concept struggles regardless of what else is done well; strong operators hold 55% or below. Bluestone spent most of 2025 above the caution line; every month of 2026 has been below it, and it has fallen every month since January. This near-sixteen-point improvement on falling comparable-day demand is why the same store that lost money in the first half of 2025 is solidly profitable now, and it is the foundation the second-location economics rest on.

Ingredient cost runs roughly ten points below prior year in every month, verified against actual vendor payments: the business paid $22,140 less for food and supplies this quarter than the same quarter last year, on slightly higher sales, through a deliberate shift from broadline distribution to direct and specialty suppliers. The improvement is structural, and conservatively stated — the books record more cost than the payments support.

The payroll question, answered. The labor line carries three posting distortions — August 2025 inflated by last year's accrual errors, October 2025 understated by $26,400 of wages parked below the operating line, and March–April 2026 tangled by accrual reversals. After adjusting all three, the improvement is genuine and independently confirmed: the point-of-sale system shows the same 27 employees processed 9% more orders while payroll cash fell about 15% — shorter shifts and better scheduling, not headcount cuts. The true 2026 labor run-rate is roughly 26–28% of revenue; planning should use that figure, not the flattered 20–23% the raw books show for May and June.

H1 measure (fees restored, payroll adjusted)20252026ChangeAssessment
COGS % of revenue41.4%29.8%−11.6 ptStructural — sourcing shift
Labor % of revenue30.7%26.6%−4.1 ptReal — hours per order
Prime cost %72.1%56.4%−15.7 ptDistressed to near-strong (line: 55%)
Gross margin %58.6%70.2%+11.6 ptMirrors the COGS line

Corrections Outstanding — July Close

ItemProfit effectStatus
Card processing fees not recorded April–June−$10,240To correct
Settlement recorded as an asset−$38,400To correct
Credit card interest unposted (estimate)−$5,310Confirm on statement
Loan payments coded as kitchen supplies+$6,780To correct
Personal spending in business expenses+$6,020Reclassify to draws
Net effect on reported year-to-date profit−$41,150

Every item is a recording question, not a trading one — cash is unaffected by all of them. Resolving them in the July close is far cheaper than at year end. Separately: no depreciation has been recorded in eighteen months, and roughly nineteen months of merchandise stock ($23,600) should be valued honestly with reordering paused until sales recover.

Forward Look — 30 To 90 Days

WhenWhatWhy it matters
JulyPeak season; the corrections closeHighest-cash month; the close is the test that the books are fixed
AugustPeak trading (~$128K projected)Hold the labor gain — last year's schedule blowout was exactly here
SeptemberShoulder season begins (−31% from August)Where last year's slide to the November low began
Oct–NovThe seasonal testProjection holds cash above $124K against last year's $13,600 trough — the single most important number to track
OngoingOff-site baking; the scoop traffic questionCost per unit still unpriced; the scoop decline deserves an answer before the concept is replicated

Sources: general ledger and statements (18 months); point-of-sale line-item data (226,400 receipt lines, reconciled to the ledger within 3%); vendor payment and payroll cash analysis. Comparable-day analysis excludes Tuesdays from both years. Adjustments stated in the margin section.

Confidential — GCM Enterprise

The number behind the number

Reported growth decomposed into a calendar effect and a real decline. An average hides that. Receipts don't.

Verified against cash

Margin gains checked against actual vendor payments and payroll cash — not just the entries in the books.

Recording vs trading

Bookkeeping problems separated from real performance, each with its profit effect priced and a date to fix it.

Every number traceable

Each figure traces to a named source: what was analyzed, how many lines, and how closely it reconciles to the ledger. You can check the work.

Book a 30-minute call Thirty minutes · No obligation · Typically $1,000–$3,000 a month, fixed

The Method

I break the business down to its levers.

Most finance starts with last year's template. I start with the question underneath it: how does this business turn capital into cash? Strip the template away and every business reduces to the same machine — only the dials differ.

Pricing

What you charge, and how it flexes.

Overhead

The cost of simply staying open.

Cost to deliver

What each job truly consumes.

Labor

The largest, stickiest line.

Contract terms

When cash comes in and goes out.

Cash-flow cycle

The gap between paying and getting paid.

Capital

What's invested — and what it must earn.

Move any leverthe model projects the impactwhere you land in 6–12 months

This is why the sector doesn't change the method. On $5M of revenue, one point of margin is $50,000 a year.

Projections are model estimates based on stated assumptions — not guarantees.

Beyond The Ledger

Your accounting system knows the dollars. It doesn't know what happened.

A P&L can tell you revenue rose 4.6%. It can't tell you an added trading day brought in more than the whole increase while sales on the days open in both years fell 5.1%. The work starts from your books. Where it helps answer a question, I add data from systems you already use and reconcile it to the ledger.

Sales detail

Line-item revenue

Receipt, order or invoice lines from your point-of-sale system, online store or invoicing, reconciled to the ledger: product or job mix, transaction counts, average ticket, timing. Where a revenue number becomes a reason.

Vendor payments

Cost, verified

What actually left the bank for materials and supplies, checked against what the books recorded — so a sourcing win can be proven rather than asserted.

Payroll & scheduling

Hours against output

Payroll cash and hours against orders produced. The difference between better scheduling and quietly losing people shows up here.

Jobs, bookings, pipeline

Forward demand

Backlog, win rates, unbilled work and job-level yield from the systems your crews already use — the leading indicators a P&L structurally cannot see. For an HVAC or trades company: job margin, technician hours against revenue, service-agreement revenue and the shoulder-season cash dip.

ERP & inventory

Cost, by product line

Standard against actual cost, purchase-price and usage variances, inventory aging and work in progress from your ERP, reconciled to the ledger. Where a margin change becomes a product line, a supplier or a plant.

Nearly all of this data already sits in systems you pay for every month. It's added read-only or as a monthly export, and only where it answers a question.

Your Data & The AI

What I take, and what I don't.

Handing your financials to anyone deserves a straight answer about what happens to them. Here is mine.

Access matched to the work

For analysis-only engagements, access is read-only. Where I'm engaged for bookkeeping, I record and adjust entries in your accounting system — that's the job. In every engagement, GCM never has signature authority on any account, never initiates or approves payments or transfers, and never holds client funds.

Your data trains nothing

Your financials are used to analyze your business and nothing else. The AI model runs under commercial terms that exclude training on your data.

Software calculates. AI drafts. I sign.

Software rebuilds the model, reconciles the statements and runs the scenarios. An AI model drafts the written findings from those figures. It does no arithmetic, doesn't log into your accounts and decides nothing. I check every finding and sign the brief.

Confidential by default

Your numbers, your name, your strategy. Nothing published, nothing shared, no logo wall.

Questions

The things owners ask first.

Is this the same as hiring a fractional or outsourced CFO?

No. A fractional or outsourced CFO joins your leadership team and runs finance: cash, banks, lenders, the finance staff. I don't, and I never move money or sign for the company. I run the analysis a good CFO would run: your model rebuilt each month, risks named and tracked, recommendations priced in dollars, and a monthly meeting where I tell you what I'd do. You make the calls. If you need someone to run finance, hire a CFO; this also works alongside one.

Do you replace my bookkeeper, controller or CPA?

No. Your CPA keeps tax and filings. Your bookkeeper or controller keeps the books and the monthly reporting; I take their close and model what comes next. I don't redo it: where a figure doesn't tie to bank, payroll or vendor payments, I list the item, its profit effect and the source, and they decide the entry. If you'd rather hand me the books, I can keep them.

What if my books are a mess?

Common. Within the first week I tell you what's usable. If the books can't support the analysis yet, I can keep them myself or work alongside your bookkeeper to catch them up, quoted separately, and I tell you when the 15 days start. The specimen brief on this page found bookkeeping corrections that cut year-to-date profit by a net $41,150, and kept them apart from real performance.

What do I get from the 30-minute call?

A plain read on what I'd look at first in your numbers, what read-only access it takes, and whether your books can support the analysis now or need catching up first. If it's a fit, I quote a fixed monthly fee after the call, typically $1,000 to $3,000 a month. Your first deep analysis arrives within 15 days of read-only access to books that can support it; if yours need catching up first, I tell you on the call when the 15 days start.

What does the AI actually do?

It runs the analysis. Each month the system rebuilds your financial model, reconciles the figures, and names every risk and opportunity it identifies — including the ones that contradict the headline. It doesn't log into your accounts, doesn't move anything, and doesn't decide. I review every finding, correct what's wrong, and sign the brief. You set the strategy.

Who sees our books, and what happens to the data?

Me and the software, plus the AI provider that drafts findings from calculated figures. Analysis access is read-only and you can remove it at any time. Your data isn't used to train AI models: the model runs under commercial terms that exclude it.

What does it cost, and how long is the commitment?

A fixed monthly fee, typically $1,000 to $3,000 a month depending on the size of the business and what you want answered. I quote it after the call once I've seen the state of your books, and it's never a share of anything. Any catch-up bookkeeping is quoted separately. There's no long-term contract: you can stop after the first deep analysis and keep it; after that it's month to month, with no lock-in.

What size company is this for?

Owner-run companies from roughly $1M to $100M in revenue, in any sector. Below that the analysis usually outruns the decisions it would inform.

Book a 30-minute call 30 minutes · month to month

Also Available

Books not ready? I can keep them. Spending on ads? I check them.

01

Bookkeeping

Catch-up and monthly bookkeeping: books brought current, then closed on time every month, so the analysis has clean inputs.

02

Monthly Reporting

Financial statements delivered on schedule, in a format you actually read and use.

03

Financial Statement Analysis

Trend, margin and cash-flow analysis of existing statements — a lighter engagement than the full model.

04

Marketing Verdict

For companies with real ad spend: what Google and Meta claim, checked each month against what your books show was sold and kept. Same read-only access, same signature. On its own or alongside the monthly review, for its own fixed fee.

Let's Talk

See what the analysis finds in your numbers.

Thirty minutes with me, Graham Miller. Tell me your industry, roughly what you do in revenue, and the question that keeps coming back. You leave knowing what I'd look at first in your numbers and whether your books can support the analysis now. If it's a fit, I quote a fixed monthly fee, typically $1,000 to $3,000 a month. Your first deep analysis arrives within 15 days of read-only access to books that can support it; if yours need catching up first, I tell you on the call when the 15 days start.

Graham Miller · GCM Enterprise LLC · Virginia Beach, VA